
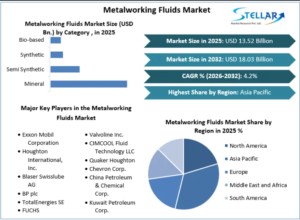

The global Metalworking Fluids Market is undergoing a fundamental structural transformation, pivoting away from traditional petroleum-derived lubricants toward high-performance bio-based and synthetic formulations, according to a comprehensive intelligence report released by Stellar Market Research. Valued at USD 13.52 billion in 2025, the market is projected to reach USD 18.03 billion by 2032, expanding at a Compound Annual Growth Rate (CAGR) of 4.2% over the forecast period (2026–2032).
Metalworking fluids (MWFs)—essential coolants, lubricants, and anti-corrosive agents used in metal cutting, grinding, drilling, and forming—are experiencing a technical evolution. While historical demand relied heavily on low-cost mineral oil formulations, modern manufacturing tolerances and high-temperature machining of advanced materials (such as titanium, carbon-composite matrices, and automotive-grade aluminum alloys) require specialized fluids capable of extreme pressure resistance.
Key Findings from the Report
-
Market Valuation: Global market size reached USD 13.52 billion in 2025 and is on track to touch USD 18.03 billion by 2032.
-
Category Dominance: Mineral Oil-Based Fluids retained the dominant market share in 2025 due to cost efficiency and legacy machinery compatibility, but Synthetic and Bio-Based categories represent the fastest-growing segments through 2032.
-
Function & Application Leaders: Neat Oils and Water-Soluble Cutting Oils dominate structural machining, with removal/cutting fluids accounting for the largest operational volume across heavy industrial machinery.
-
Regional Supremacy: Asia Pacific leads the global market with over 40% revenue share in 2025, propelled by expanding automotive production, infrastructure investments, and industrial machinery manufacturing in China, India, Japan, and South Korea.
-
Emerging Growth Corridor: North America and Europe demonstrate rapid adoption of high-tier bio-lubricants, spurred by aggressive corporate ESG targets and strict workplace aerosol standard enforcement.
-
Cost Impact Ratio: According to industrial research cited in the report, while MWFs comprise less than 5% of total plant fluid expenditures, their performance directly influences over 40% of a facility’s overall operational budget through tool lifecycle management and surface-finish yield rates.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/metalworking-fluids-market/2381
Market Drivers and Restraints
Industry Drivers
-
Surge in Automotive Lightweighting and EV Chassis Machining: The global push for reduced vehicle emissions has accelerated the use of high-strength aluminum alloys and composites. Machining these lightweight components demands advanced synthetic MWFs that effectively manage heat dissipation and chip removal without causing intergranular corrosion.
-
Rapid Adoption of Sustainable Bio-Based Formulations: Vegetable oil and ester-derived MWFs deliver superior lubricity, higher flash points, and environmental biodegradability (70%–100% vs. 15%–35% for straight mineral oils), reducing chemical waste liability for manufacturing facilities.
-
Heavy Equipment and Infrastructure Expansion in Developing Nations: Massive industrialization across Asia Pacific and Latin America continues to spur baseline volume demand for metal cutting, grinding, and forming fluids across construction and agricultural machinery manufacturing.
Industry Restraints
-
Occupational Health Regulations and Hazardous Waste Disposal Costs: Exposure to MWF mist and microbial contamination can cause contact dermatitis, hypersensitivity pneumonitis, and respiratory distress. Strict compliance limits (e.g., NIOSH TWA recommendations of 0.4 mg/m³) require expensive ventilation infrastructure and biological monitoring.
-
Fluctuating Raw Material Prices: Base oil and additive price volatility directly impacts manufacturer margins, prompting cost-sensitive small and medium enterprises (SMEs) to delay upgrading to premium bio-synthetic fluid lines.
Technology, Regulation, and Sustainability Trends
-
IoT-Enabled Fluid Management: Smart sensors and automated concentration monitoring units are being deployed within metal-machining sumps to track pH levels, fluid concentration, and bacterial contamination in real time, dramatically extending fluid lifespan and reducing premature fluid disposal.
-
MQL (Minimum Quantity Lubrication) Innovation: Near-dry machining techniques utilizing ultra-fine aerosol droplets are reducing fluid consumption volume while demanding hyper-refined, non-toxic bio-esters.
-
ESG & Regulatory Alignment: Stricter waste-water disposal laws and global corporate carbon-neutrality pledges are compelling industrial firms to adopt closed-loop fluid recycling systems and readily biodegradable formulations.
Regional Insights
-
Asia Pacific: Remains the primary revenue engine. Rapid industrialization, dominant automotive assembly networks in China and India, and rising investments in aerodrome infrastructure and defense production fuel strong volume demand.
-
North America: Characterized by high penetration of synthetic MWFs and early adoption of automated fluid management technologies. Aerospace manufacturing hubs in the U.S. drive premium fluid consumption.
-
Europe: Leads in regulatory enforcement (REACH, EU Ecolabel). Demand is heavily skewed toward bio-based, chlorine-free, and secondary-amine-free fluid systems.
Recent Industry Developments (Last 12–18 Months)
-
FUCHS Group (2025): Expanded its global production footprint by opening a specialized synthetic lubricant and bio-based metalworking fluid plant, increasing regional manufacturing capacity for high-performance cutting fluids by 25%.
-
ExxonMobil Corporation (2025): Launched an upgraded portfolio of advanced water-soluble coolants engineered specifically for high-speed machining of aerospace-grade titanium and aluminum alloys, offering up to 20% longer tool life.
-
Quaker Houghton (2025): Introduced an automated fluid-monitoring digital platform integrated with IoT sump sensors, enabling industrial facilities to track fluid degradation in real time and cut maintenance downtime by 15%.
-
Blaser Swisslube AG (2024): Formed a strategic partnership with leading CNC machine tool original equipment manufacturers (OEMs) to develop custom bio-based liquid formulations tailored for medical implant manufacturing and precision micro-machining.
-
TotalEnergies SE (2024): Unveiled a refurbished line of eco-friendly, vegetable-oil-derived metalworking fluids featuring zero secondary amines and low-boiling volatile organic compounds (VOCs) to meet stringent EU workplace safety guidelines.
Competitive Landscape
The global metalworking fluids market features a consolidated tier of multinational chemical and energy leaders alongside specialized regional formulators. Leading companies focus on portfolio expansion through bio-based R&D, IoT-driven fluid management services, and strategic partnerships with CNC machinery builders.
Key Market Players Include:
-
Exxon Mobil Corporation
-
Quaker Houghton (Houghton International Inc.)
-
Blaser Swisslube AG
-
BP plc (Castrol)
-
TotalEnergies SE
-
FUCHS Petrolub SE
-
Chevron Corporation
-
Idemitsu Kosan Co., Ltd.
-
ENEOS Corporation
-
Master Fluid Solutions
Analyst Commentary
“The metalworking fluids sector is no longer merely a consumable line-item in machine shop operations—it has become a strategic lever for operational efficiency and ESG compliance,” stated a Senior Research Analyst at Stellar Market Research. “As aerospace and electric vehicle manufacturers transition to complex alloys and tighter tolerances, fluid chemistry must evolve alongside tool tooling technology. The shift toward bio-based, micro-emulsion, and IoT-monitored synthetic formulations will define market leadership over the next decade.”
Future Outlook
Through 2032, the metalworking fluids market will be shaped by the convergence of digital monitoring, bio-synthetic chemistry, and advanced alloy machining. While mineral oils will retain a baseline presence in cost-sensitive markets, growth velocity will center on low-toxicity, long-life synthetic and vegetable-derived coolants. Formulators that offer integrated “Fluid-as-a-Service” models—combining chemical supply with automated monitoring and circular recycling solutions—are best positioned to capture market share in an increasingly regulated industrial landscape.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/metalworking-fluids-market/2381
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656