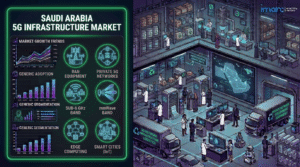

IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Saudi Arabia 5G infrastructure market. The Saudi Arabia 5G infrastructure market size was valued at USD 199.5 Million in 2025 and is expected to reach USD 4,892.8 Million by 2034, exhibiting a CAGR of 42.69% during 2026-2034, driven by aggressive spectrum allocation by the Communications, Space and Technology Commission (CST), intensifying network investment among stc, Mobily, and Zain KSA, and Vision 2030’s digital transformation agenda.
The market is moving from initial urban coverage into a phase of deep capacity densification, Standalone (SA) network expansion, and private 5G deployment for industry verticals. Competition among the Kingdom’s three mobile network operators is compounding demand for high-speed, low-latency connectivity as data-intensive applications, IoT deployments, and edge computing use cases scale across residential, commercial, government, and industrial end users. The market remains structurally import-dependent, with no domestic manufacturing of active Radio Access Network (RAN) components, keeping global vendors such as Ericsson, Nokia, and Huawei central to the Kingdom’s buildout.
Saudi Arabia 5G Infrastructure Market at a Glance:
- Market Size (2025): USD 199.5 Million
- Forecast Market Size (2034): USD 4,892.8 Million
- CAGR (2026-2034): 42.69%
- Base Year: 2025
- Historical Period: 2020-2025
- Forecast Period: 2026-2034
- Leading Network Architecture (2025): Non-Standalone (NSA), on the back of faster rollout by leveraging existing 4G infrastructure
- Leading Mobile Network Operator by 5G Base Station Procurement: stc Group, accounting for an estimated 40-45% of base station purchases
How AI is Reshaping the Future of the Saudi Arabia 5G Infrastructure Market
- AI-Driven Network Automation and Self-Optimizing Networks: stc Group’s “Fusion” partnership with Ericsson is scaling AI-driven network automation across the operator’s 5G footprint, while AI-based traffic prediction and self-organizing network (SON) tools are helping operators manage densification in high-traffic urban zones such as Riyadh, Jeddah, and Dammam.
- AI-Enabled Massive Event Connectivity: Operators are deploying AI-based capacity forecasting and dynamic spectrum management to support temporary but extreme-demand deployments for Riyadh Season, the Jeddah Formula One Grand Prix, and Hajj and Umrah pilgrim flows, where hundreds of thousands of simultaneous users must be served on 5G infrastructure originally engineered for steady-state loads.
- AI-Powered Edge Computing and Real-Time Analytics: 5G infrastructure is enabling edge computing deployments that cut latency to milliseconds, supporting AI-enabled video analytics, smart building management, and industrial automation use cases that are becoming central to enterprise 5G contracts across the Kingdom’s smart city and industrial diversification programs.
Grab a sample PDF of this report: https://www.imarcgroup.com/saudi-arabia-5g-infrastructure-market/requestsample
Saudi Arabia 5G Infrastructure Market Trends and Drivers:
Operator rivalry is the single biggest structural driver of infrastructure spend, with stc, Mobily, and Zain KSA having collectively committed billions of Saudi riyals to network buildout since 2020 as each races to expand coverage, densify capacity, and layer on 5G-Advanced capabilities. Rising demand for high-speed data connectivity, as individuals and businesses lean further into 4K video streaming, augmented and virtual reality, and IoT, is pushing operators to move beyond basic coverage toward capacity-led densification through small cells and massive MIMO upgrades, while the expansion of IoT use cases across smart cities, connected vehicles, industrial automation, and healthcare is widening the addressable base for network infrastructure spend.
Government-backed spectrum policy is a structural, not incidental, advantage. The Communications, Space and Technology Commission (CST) has positioned the Kingdom as the first country in Europe, Africa, and the Middle East to license the 600 MHz band for mobile telecommunications, and Saudi Arabia now ranks highest globally in terms of assigned IMT spectrum in bands below 6 GHz, a foundation that is allowing operators to roll out coverage in remote areas, along highways, and across border entries and railways faster than in most comparable markets. Reported 5G download speeds already rank among the fastest globally, underscoring the maturity of the underlying infrastructure relative to the market’s still-early revenue base.
Infrastructure sharing is emerging as the next efficiency lever. With a high degree of parallel infrastructure built up during the early competitive rollout phase, the government is encouraging colocation and network sharing to lower deployment costs, exemplified by stc Group’s towerco TAWAL and its Public Investment Fund-backed consolidation, alongside shared indoor 5G Standalone deployments between operators, equipment vendors, and neutral-host providers that have demonstrated substantial reductions in indoor deployment costs. Layered on top, Vision 2030’s digital economy priorities and mega-event connectivity mandates for Expo 2030 and the FIFA World Cup 2034 are compressing rollout timelines for standalone architecture and higher-frequency spectrum bands.
Government Schemes and Vision 2030 Initiatives Driving Demand:
- National Spectrum Auctions by CST: The Communications, Space and Technology Commission’s fifth IMT spectrum auction awarded 600 MHz, 700 MHz, and 3800 MHz frequencies to stc, Mobily, and Zain, lifting total licensed mobile spectrum by 27% from 1,110 MHz to 1,400 MHz and expected to contribute over SAR 25 Billion to GDP by 2030.
- Spectrum Outlook 2024-2026: CST’s proactive spectrum management roadmap, covering light licensing and spectrum trading, is designed to prepare the Kingdom’s radio infrastructure for a future of an estimated 29 billion connected wireless devices by 2030, spanning 6G, IoT, satellite, and smart city use cases.
- Vision 2030 Digital Economy Contribution Target: 5G investment is projected to contribute approximately USD 18 Billion in GDP by 2030, formally positioning connectivity infrastructure as a core enabler of the Kingdom’s non-oil economic diversification alongside tourism, logistics, and manufacturing.
- National 5G Coverage Expansion Initiative: In October 2025, stc announced a national initiative under Vision 2030 to expand 5G coverage to more than 2,000 additional sites, with a specific focus on underserved regions, supporting the Kingdom’s target of near-universal 5G availability.
- Mega-Event and Pilgrimage Connectivity Mandates: CST-coordinated readiness programs, including AI-enabled 5G infrastructure deployed for the Hajj 2026 season, alongside upcoming connectivity requirements for Expo 2030 and the FIFA World Cup 2034, are compressing timelines for standalone architecture rollout and higher-frequency densification nationwide.
Saudi Arabia 5G Infrastructure Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Communication Infrastructure:
- Small Cell
- Macro Cell
- Radio Access Network (RAN)
- Others
Macro cell deployments continue to anchor nationwide 5G coverage across the Kingdom’s highways, industrial zones, and tourist destinations, while small cell rollout is emerging as the fastest-growing communication infrastructure segment as operators shift from broad coverage toward capacity-led densification in dense urban centers such as Riyadh, Jeddah, and Dammam.
Breakup By Network Technology:
- Software-Defined Networking
- Network Function Virtualization
- Others
Software-defined networking and network function virtualization are gaining traction as operators such as stc scale AI-driven network automation partnerships, using these technologies to manage capacity dynamically across nationwide infrastructure while reducing operational costs.
Breakup By Network Architecture:
- Standalone
- Non-Standalone
Non-Standalone (NSA) architecture currently leads the market, allowing operators to leverage existing 4G infrastructure for a quicker rollout and better near-term user experience, while Standalone (SA) architecture is gaining momentum as stc, Mobily, and Zain KSA pursue full 5G capabilities, lower latency, and 5G-Advanced features through shared and independent SA deployments.
Breakup By Frequency:
- Sub-6 Ghz
- Above 6 Ghz
Sub-6 GHz spectrum remains the backbone of nationwide coverage following successive CST spectrum auctions in the 600 MHz, 700 MHz, and 3800 MHz bands, while above-6-GHz deployment is expanding selectively to support capacity-dense urban and enterprise use cases requiring higher throughput.
Breakup By End User:
- Residential
- Commercial
- Government
- Industrial
Commercial and government end users are driving early enterprise-grade 5G adoption, from smart building management and surveillance solutions to public safety and smart city networks procured by agencies such as the Ministry of Interior and the Saudi Data and AI Authority, while industrial demand is building through private 5G deployments at large industrial and logistics operators.
Breakup By Region:
- Northern and Central Region
- Western Region
- Eastern Region
- Southern Region
The Northern and Central Region leads the Saudi Arabia 5G infrastructure market, anchored by Riyadh’s role as the Kingdom’s economic and administrative capital and the concentration of smart city and enterprise 5G projects, while the Western Region benefits from dense event and pilgrimage-driven connectivity demand around Jeddah and Makkah, the Eastern Region is shaped by industrial and Aramco-linked private network deployments around Dammam, and the Southern Region represents an emerging densification opportunity as national coverage initiatives extend into underserved areas.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the Saudi Arabia 5G infrastructure market with detailed profiles of all major companies, including:
- Saudi Telecom Company (stc Group)
- Mobily (Etihad Etisalat Company)
- Zain KSA
- Ericsson
- Nokia
- Huawei Technologies
- Samsung Electronics
- ZTE Corporation
Market Concentration Analysis:
- Oligopoly Structure: The market is defined by a regulated three-operator oligopoly, stc, Mobily, and Zain KSA, with stc holding a structural advantage on the back of early 5G deployment and state-backed infrastructure through the Public Investment Fund.
- Infrastructure Consolidation Trend: The Public Investment Fund-backed tower company merger with stc’s TAWAL forms one of the region’s largest passive-infrastructure platforms, lowering network duplication and freeing operator capital for active 5G equipment spend.
- Import-Dependent Vendor Base: With no domestic manufacturing of active Radio Access Network components, global equipment vendors, led by Ericsson, Nokia, and Huawei Technologies, and a nascent Open RAN ecosystem, dominate the supply side of the market.
What Does The Full Report Cover?
If you are tracking the Saudi Arabia 5G infrastructure market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group’s report gives you everything in one place:
- Complete market sizing in value terms with forecasts covering the full 2026-2034 projection period
- Quantified growth driver analysis with impact scoring across communication infrastructure, network technology, network architecture, frequency, and end user segments
- Sub-segment breakdowns for small cell, macro cell, and RAN infrastructure, standalone and non-standalone architecture, sub-6 GHz and above-6-GHz frequency bands, and all four regions of the Kingdom, each with individual analysis
- Regional data across the Northern and Central, Western, Eastern, and Southern regions of Saudi Arabia
- Competitive profiles of leading global and national telecommunications and equipment operators with strategic landscape assessment
- Value chain analysis, market concentration assessment, and investment and growth opportunity mapping
- Latest technology trends covering AI-driven network automation, edge computing, spectrum policy developments, and Vision 2030-driven infrastructure opportunities shaping market competition across the Kingdom
Recent News and Developments in Saudi Arabia 5G Infrastructure Market
- July 2026: stc Group and Huawei deployed Saudi Arabia’s first Full Duplex network solution in Riyadh, reporting 50 Gbps transmission capacity, underscoring a shift toward higher spectral efficiency in dense urban traffic zones.
- July 2026: The Communications, Space, and Technology Commission announced the readiness of AI and 5G infrastructure for the Hajj 2026 season, supporting connectivity for one of the world’s largest simultaneous-user events.
- October 2025: stc announced a national initiative under Vision 2030 to expand 5G coverage to more than 2,000 sites, with a specific focus on underserved regions across the Kingdom.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current Saudi Arabia 5G infrastructure market size and what is its projected value?
- Which communication infrastructure segment holds the largest share in the Saudi Arabia 5G infrastructure market?
- What are the key drivers of Saudi Arabia 5G infrastructure market growth?
- Which region dominates the Saudi Arabia 5G infrastructure market and why?
- How is Vision 2030, CST spectrum policy, and AI-driven network automation reshaping infrastructure investment and competitive strategy in the Saudi Arabia 5G infrastructure industry?
- Who are the top companies in the Saudi Arabia 5G infrastructure market and what are their competitive strategies?
- What are the investment and market entry opportunities across private 5G networks, Open RAN, and infrastructure sharing in Saudi Arabia?
About Us
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-113-547-7077