
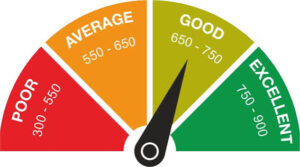

Before applying for any major form of credit, it is useful to understand how your credit profile may appear to a lender. Many borrowers begin by asking, “How do I check my credit score?” A credit score is a numerical representation of your past credit behaviour and is generally based on factors such as repayment history, outstanding balances, credit utilisation, credit mix, and recent enquiries. If you are planning to take a home loan, knowing your score in advance can help you identify possible issues before submitting an application. You can usually check CIBIL online through authorised digital channels by completing basic identity verification. While you cannot directly calculate your CIBIL score using a simple formula, understanding the factors that influence it can help you manage your credit more effectively.
What Does It Mean When I Check My Credit Score?
When you check my credit score, you are reviewing a snapshot of your creditworthiness based on information available in your credit report.
A credit report may include details such as:
- Active and closed credit accounts
- Loan and credit card repayment history
- Outstanding balances
- Credit limits
- Recent credit enquiries
- Overdue amounts, if any
The score itself is generated from this information using the credit bureau’s scoring model.
How to Check CIBIL Online
The process to check CIBIL online is generally straightforward.
Typical steps include:
- Visit an authorised credit bureau or approved financial platform.
- Enter basic personal information.
- Provide identification details, such as PAN, where required.
- Complete identity verification.
- Access the credit score and report.
Before entering personal details, make sure the platform is legitimate and uses secure verification methods.
Can You Calculate Your CIBIL Score Yourself?
Many people search for ways to calculate your CIBIL score, but the exact score cannot normally be recreated manually because credit bureaus use proprietary scoring models.
However, you can understand the key factors that usually influence it:
- Payment history: Timely repayments generally support a stronger profile.
- Credit utilisation: Using a large portion of available revolving credit may affect the score.
- Credit history length: Older accounts can contribute to a longer credit track record.
- Credit mix: A balanced mix of different types of credit may be considered.
- Recent enquiries: Multiple applications over a short period may influence the profile.
While you may not be able to calculate the exact number yourself, these factors provide useful guidance on how credit behaviour can affect your score.
Why Check Your Score Before You Take a Home Loan?
If you plan to take a home loan, reviewing your credit profile before applying can help you prepare better.
It can help you:
- Identify errors in your credit report
- Understand whether there are overdue accounts
- Review outstanding credit obligations
- Avoid unnecessary applications
- Improve your financial profile before approaching a lender
A stronger credit profile may support more favourable loan terms, although final approval depends on income, liabilities, property details, and lender policy as well.
How Often Should You Check My Credit Score?
There is no need to check your score every day. However, periodic monitoring can be useful.
You may consider checking it:
- Before applying for a major loan
- After repaying significant debt
- When you suspect an error in your credit report
- After closing or restructuring an account
- Periodically as part of financial planning
Reviewing the report regularly can also help identify unfamiliar enquiries or accounts.
Common Mistakes to Avoid
When reviewing your credit profile, avoid common errors such as:
- Ignoring overdue amounts
- Applying repeatedly after a rejected application
- Closing several long-standing accounts without considering the impact
- Using most of your available credit limit regularly
- Failing to review errors in your credit report
- Assuming the score alone guarantees loan approval
A credit score is an important indicator, but lenders usually assess the wider financial profile as well.
Summary: Check My Credit Score Before Major Borrowing Decisions
Choosing to check my credit score before applying for credit can help you understand how your borrowing history may appear to lenders.
If you plan to take a home loan, it is useful to check CIBIL online, review your credit report, and address any issues before applying. Although you cannot usually calculate your CIBIL score manually, understanding the factors that influence it can help you make better financial decisions.
With timely repayments, sensible credit usage, and regular monitoring, you can gradually improve credit score health and maintain a stronger borrowing profile over time.