

Retirement planning is a long-term process that requires more than simply saving money. People need to consider how much they may need in the future, how their financial circumstances could change, and how investments can support their goals over time. A structured investment strategy can make it easier to organize these decisions and monitor progress.
Portfolio Management can play an important role in connecting investments with retirement objectives. By considering asset allocation, risk, investment performance, income needs, and changing financial circumstances, investors can build a more organized approach to preparing for retirement.
Understanding Retirement Investment Goals
Retirement goals can vary significantly from one person to another. Some people may want to maintain their current lifestyle, while others may plan to travel, support family members, purchase property, or manage future healthcare and living expenses.
Before making investment decisions, it is useful to define what retirement means financially. Clear goals can provide a foundation for deciding how much to save, how long investments may remain invested, and what level of investment risk may be appropriate.
Creating a Long-Term Investment Strategy
Retirement planning often involves a long investment horizon. This allows investors to think beyond short-term market movements and focus on long-term financial objectives.
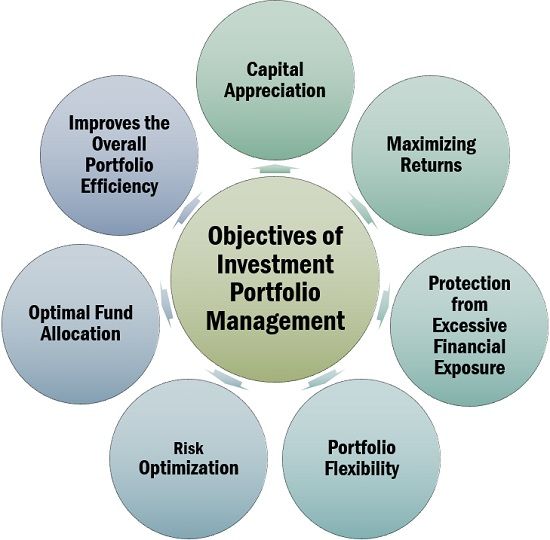
Portfolio Management helps organize investments around these objectives. A structured strategy can consider the investor’s time horizon, financial resources, expected contributions, and desired retirement income while maintaining a suitable balance between growth and risk.
Assessing Risk Tolerance
Risk tolerance is an important part of retirement planning. Investors may have different levels of comfort with market fluctuations depending on their financial position, age, investment experience, and retirement timeline.
A portfolio designed for a long-term retirement goal may need to balance growth opportunities with protection against excessive volatility. Reviewing risk regularly can help ensure that the investment approach remains aligned with changing circumstances.
Managing Asset Allocation
Asset allocation refers to how investments are distributed across different asset categories. Depending on the investor’s circumstances, a portfolio may include equities, bonds, cash, property-related investments, or other assets.
Portfolio Management can help monitor whether the allocation continues to reflect retirement objectives. As financial circumstances and market values change, the portfolio may gradually move away from its intended allocation and require review.
Using Diversification for Retirement Planning
Diversification involves spreading investments across different assets, sectors, regions, or other categories. Its purpose is to avoid relying too heavily on a single investment or area of the market.
For retirement planning, diversification can help create a more balanced investment structure. It can also reduce the effect that poor performance in one investment category may have on the overall portfolio, although diversification cannot eliminate investment risk.
Monitoring Investment Performance
Retirement planning requires regular progress checks. Investors can compare portfolio performance with their financial objectives and review whether their savings and investment strategy remain on track.
Rather than focusing only on short-term returns, investors can consider performance over appropriate time periods. Portfolio Management provides a framework for reviewing investment results alongside risk, costs, contributions, and broader retirement goals.
Planning for Retirement Income
Accumulating wealth is only one part of retirement planning. Investors also need to consider how their assets may eventually provide income.
Retirement income can come from different sources, such as pensions, investment income, savings, or other financial resources. Understanding these sources can help investors consider how their portfolio may support regular expenses after they stop working.
Adjusting the Strategy as Retirement Approaches
Investment priorities may change as retirement becomes closer. During the earlier stages of saving, investors may focus more heavily on long-term growth. As retirement approaches, preserving capital and preparing for income needs may become increasingly important.
A regular portfolio review can help investors identify whether adjustments are appropriate. Changes should be based on individual objectives and circumstances rather than short-term market reactions.
Considering Inflation
Inflation can reduce the purchasing power of money over time. Retirement planning therefore needs to consider whether future savings and investment income will be sufficient to cover rising living costs.
Portfolio Management can incorporate inflation considerations when reviewing long-term investment objectives. Investors may consider how different asset types could contribute to maintaining purchasing power while remaining consistent with their risk tolerance.
Managing Investment Costs
Investment costs can have a meaningful effect on long-term results. Management fees, transaction charges, fund expenses, and other costs can gradually reduce the amount of money available for retirement.
Reviewing these expenses regularly can help investors understand the actual cost of maintaining their investment strategy. A well-organized portfolio review considers costs alongside expected returns, risk, and financial objectives.
Rebalancing the Retirement Portfolio
Market movements can change the proportions of different investments within a portfolio. For example, one asset category may grow faster than others and become a larger part of the overall allocation.
Rebalancing can help bring the portfolio closer to its intended structure. The appropriate timing and method depend on the investor’s circumstances, tax considerations, transaction costs, and investment strategy.
Preparing for Different Retirement Stages
Retirement is not a single financial stage. Investors may experience different needs during the early, middle, and later years of retirement.
Early retirement may involve greater spending on travel or lifestyle activities, while later years may involve different priorities. Planning for changing needs can help investors think about how their assets, income, and spending requirements may evolve.
Maintaining an Emergency Reserve
Retirement portfolios should not necessarily be the only source of financial security. Maintaining appropriate liquid savings can help cover unexpected expenses without requiring investors to sell long-term investments at an inconvenient time.
The amount of emergency savings needed depends on personal circumstances, regular expenses, health-related considerations, and other financial resources. Keeping liquidity in mind can form an important part of broader retirement planning.
Reviewing Retirement Goals Regularly
Financial goals can change over time. Marriage, family responsibilities, career changes, property purchases, inheritance, or changes in expected retirement age can all influence retirement planning.
Regular Portfolio Management reviews can help investors update their strategy as circumstances change. Reviewing goals alongside portfolio performance ensures that investment decisions remain connected to current priorities.
Keeping a Long-Term Perspective
Market volatility can create uncertainty, especially when investors regularly check short-term portfolio movements. Retirement planning generally requires a longer perspective because investment decisions may span several decades.
A disciplined approach can help investors focus on their objectives rather than making frequent decisions based solely on short-term market changes. Regular reviews can provide opportunities to make thoughtful adjustments when circumstances genuinely change.
Final Thoughts
Retirement planning requires a coordinated approach to saving, investing, risk management, income planning, and long-term financial goals. Portfolio Management can help bring these elements together by providing a structured way to monitor investments and adjust strategies over time.
By setting clear objectives, managing asset allocation, diversifying investments, reviewing performance, considering inflation and costs, and preparing for changing income needs, investors can develop a more organized retirement strategy. Regular reviews are important because financial circumstances and retirement goals can evolve.
A strong retirement strategy is not about predicting every future market movement. It is about creating a thoughtful financial framework that can be reviewed and adjusted as life changes. Investors should consider their individual circumstances and seek qualified financial advice where appropriate.